Your buyers ask AI who to pick. Make sure it’s you.
Gets you selected acrossChatGPTClaudeGeminiPerplexity
RocMode shows you whether AI picks you or your rival, finds the work that changes it, builds that work, and sends it to you to approve. Then it proves what moved.
We ask ChatGPT, Claude, Gemini and Perplexity the questions your buyers ask, and show where they pick you and who they pick instead. Free, no login. What’s the Score? Or sign up free and try everything for 14 days.
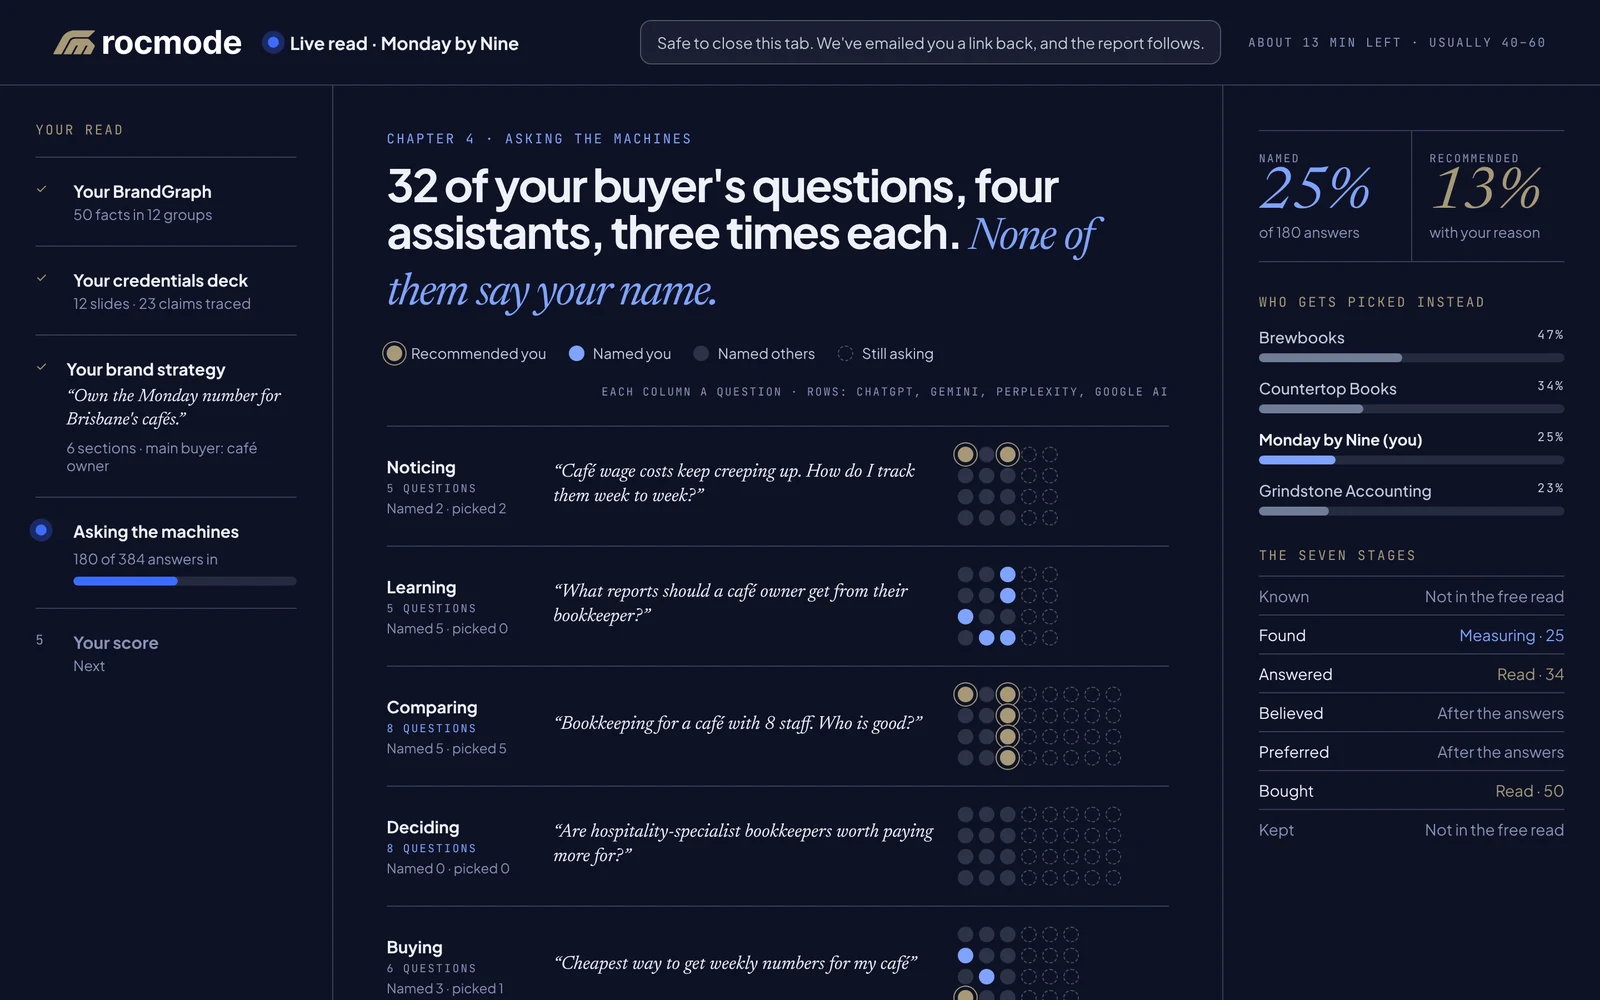
RocMode · Live read · Monday by Nine (example)
Asking ChatGPTBefore
The AI marketing and sales platform
Marketing and sales, rebuilt for the age of AI.
Your website in. A whole marketing and sales team’s work out. RocMode learns your brand from your site, then does the work: strategy, website, ads, social, PR, partners, email, design, and the deck that wins the deal. You approve every piece.
Other tools do one job. This does all of them, as one story.
Other AI guesses. This works from your facts and proof.
Other tools stop at the post. This follows it to the signed deal, and learns what won.
How it works
KnowWhere you really standActWhat to fix firstCreateWe build the work. You approve itProveDid it move?
Know · Step 1 of 10
It gets you. It gets your customers. It connects the dots.
Everything about your brand, your buyers and your rivals, sorted and connected.
Then it works out what to say, where, when and why. It’s the brain behind every step.
Builds: Customers · Offerings · Rivals · Proof
RocMode · BrandGraph · sample data
Following one momentCISO · Comparing · “Who’s the best managed security provider for a hospital group?”Moment found
Brand core3 found
Voice3 found
Visual identity3 found
Products and services3 found
Pricing3 found
Personas and markets3 found
Pains, gains, jobs3 found
Journeys and objections3 found
Proof and trust3 found
Content3 found
Competitors and partners3 found
Team2 found
Halvard Security35 facts
Two hospital case studies/partners
FactClaimProofAI-suggestedExample: Halvard Security, an invented managed security provider.
Reading halvardsecurity.com.au, socials, reviews and listings…
Halvard SecurityBrandGraph
12areas, all connected
3personas
15moments
6rivals
Sample data
Your customers
Customers
›
Personas
›
Journeys
›
Pains, jobs, objections
›
Moments
What you sell
Products and services
›
Offerings
›
Value proposition
›
Differentiation
Your rivals
Competitors
›
Industry
›
Expectations
›
Gaps to exploit
Moments + offerings
Opportunities
›
Campaigns
›
Ads
›
Sales
Content gaps
›
Content
›
Website
So it knows
What to say.Where. When. Why.
Moment foundCISO · Comparing · “Who’s the best managed security provider for a hospital group?”
Know · Step 2 of 10
Your strategy, from everything it knows.
Positioning built from your offerings and the gaps your rivals leave.
Claims you can’t back get cut before anyone sees them.
Seen isn’t selected. AI picks the brands it can tell apart.
Every era of marketing had its visibility number, and AI mentions are just the newest. Most AI tools still sell you visibility. But being mentioned isn’t being chosen, and for the first time you can measure the pick itself.
BroadcastAwareness
Media buyingReach
SearchRankings
SocialFollowers
AIMentions
What countsSelected
What AI made cheap
Making things.
Posts, pages, ads and reports in minutes
Anyone with a login can do it
Your competitors have the same tools
Sell on volume and you compete on price.
What AI made measurable
Being chosen.
Brand ABrand BYouBrand CBrand D
Buyers ask AI who to pick, and it names a few brands
You can ask the same questions and see who’s named
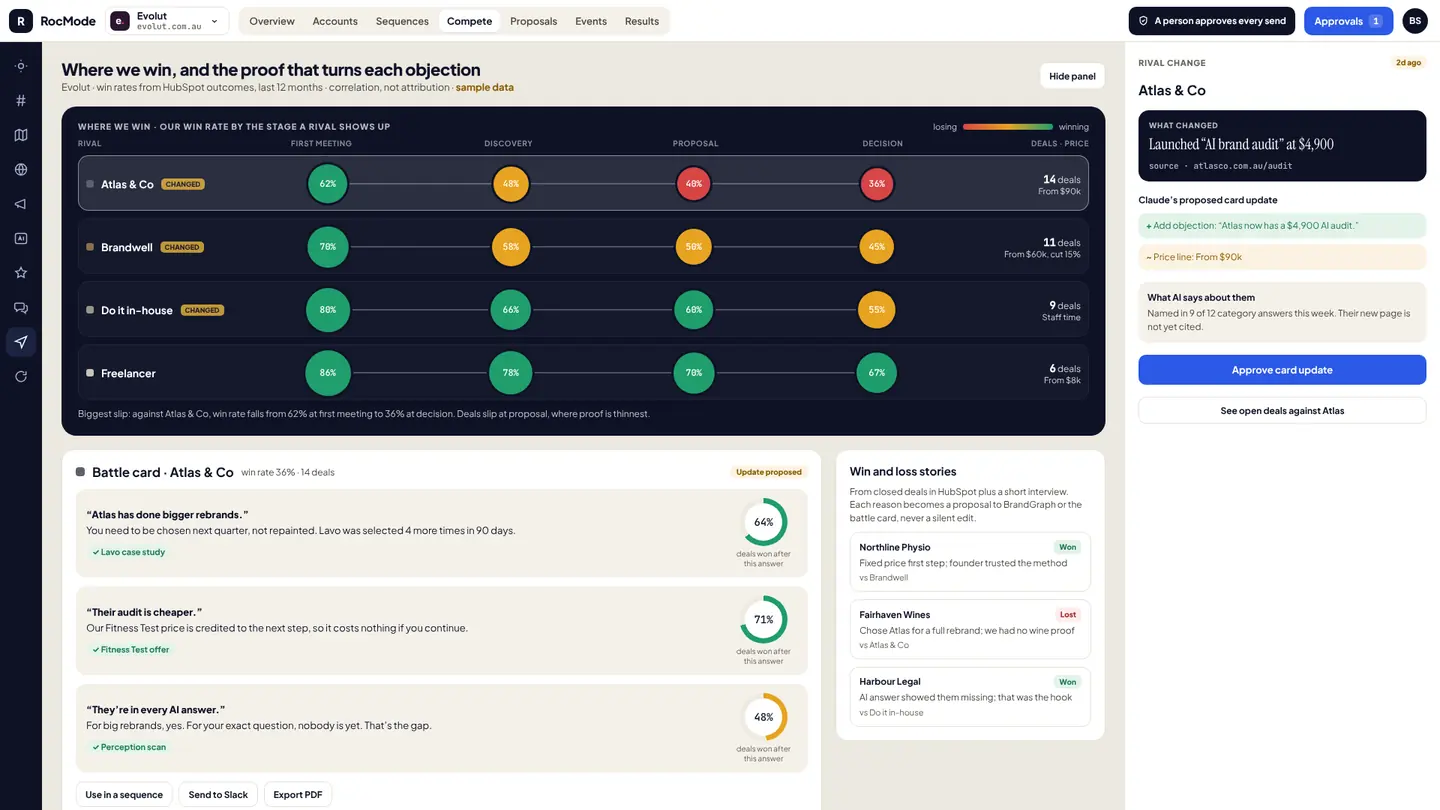
So you can see, moment by moment, where you win and lose
Compete on this and you compete on results.
See it on your brand
See how often AI picks you. Free.
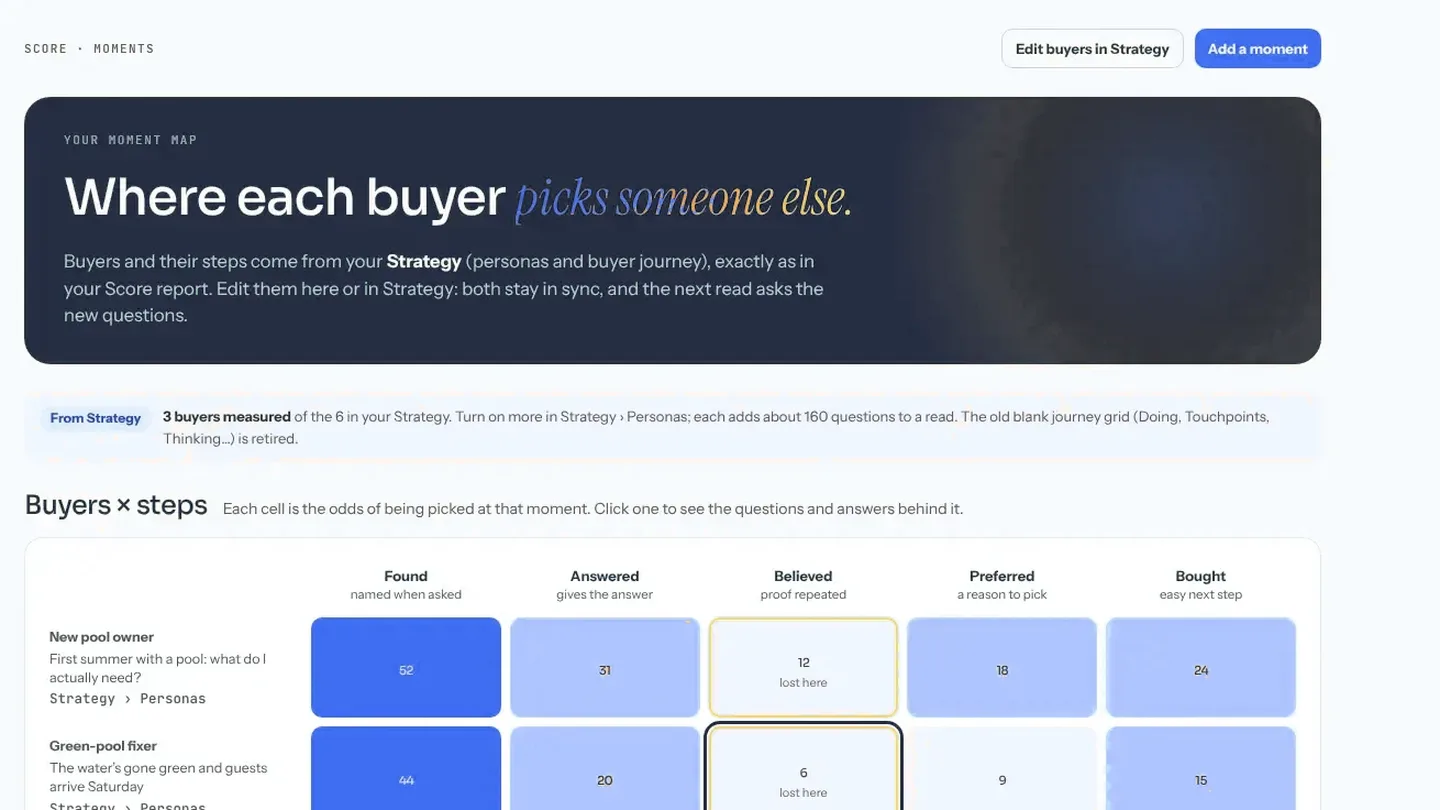
We ask the AI assistants your buyers use the questions they really ask, many times each, at every step of their journey. Then we show where you’re picked, where you’re passed over, and who wins instead.
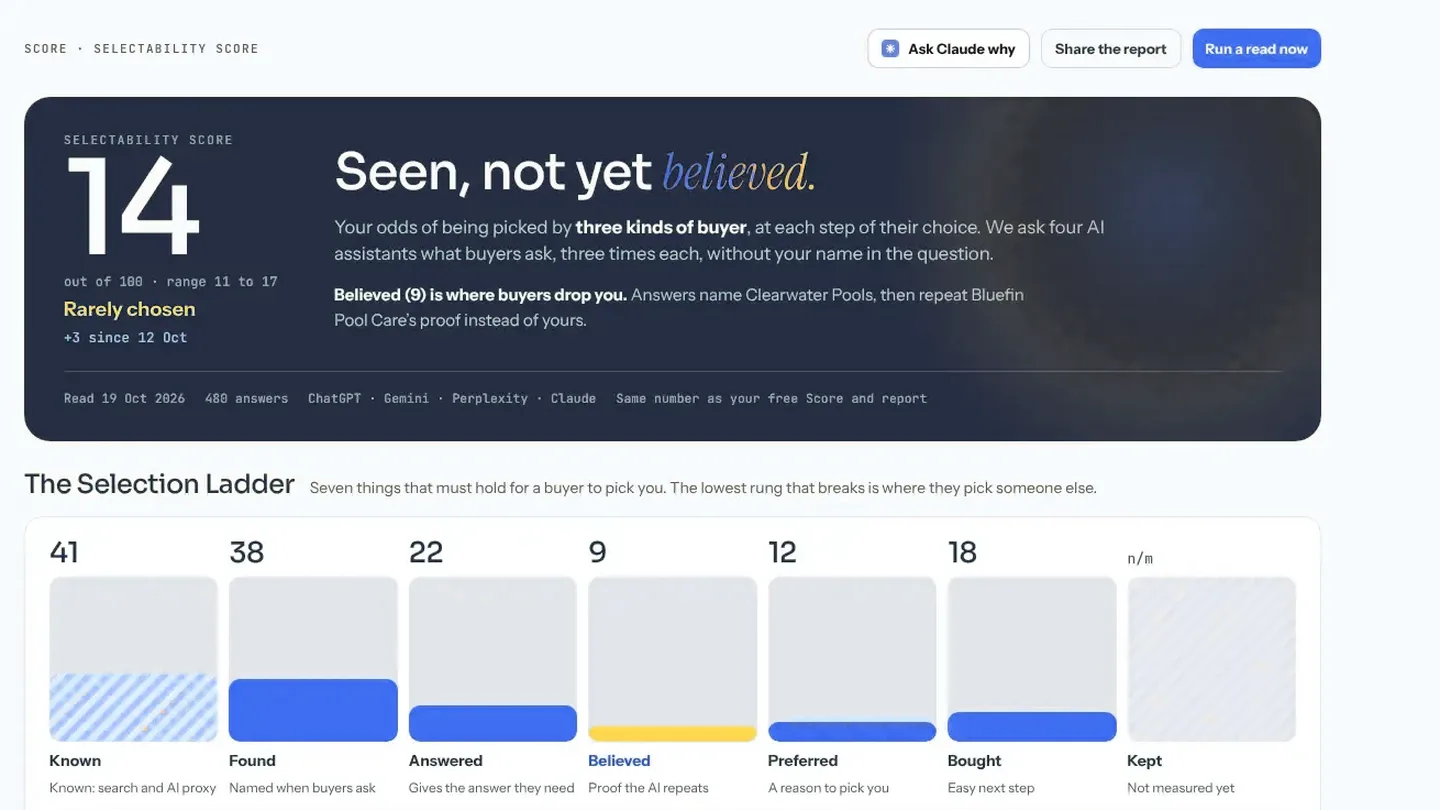
Your free Selectability Score asks the AI assistants the questions your buyers ask, without your name in them. You see who gets picked, at which moment, and the three gaps to fix first.
The decisions I've put off longest have always been hires. I've been notoriously bad at hiring, in three ways that feed each other.
I wait too long to hire for senior roles, usually three to six months past the point I knew I needed someone. When I do hire, I rarely land the right person, and I suspect that's because I want too much from one person. And because I've waited so long, the new hire gets rushed through their first weeks and thrown in at the deep end. Too often they're gone within three to six months, sometimes by their choice and sometimes by mine.
The worst one still makes me wince. I needed what was, in effect, a studio manager. I found someone who'd done that exact job in-house, with a team about our size and much the same scope. Great references. On paper, a legend.
In reality, the worst hire I've ever made. They couldn't juggle more than one client. They treated clients as the enemy and talked constantly about how stupid they were, and it showed. They routinely put clients offside. Before it ended, they'd cost me clients and I'd paid out refunds.
Looking back, the waiting was fear, and that hire is why. A bad senior hire costs recruitment fees, delayed projects, refunds, lost clients, lost sales and, worst of all, my focus. I could feel all of that far more sharply than I could picture the upside of a good hire. So I put it off, and putting it off made the bad outcome more likely.
What would have made it safe to say yes? Proof that the person had done the exact jobs I needed, in an agency, not just in-house. Most candidates had done some of them, and rarely all. Or, better still, some kind of guarantee that it would work. As far as I know, nobody offers one.
Every buyer I've sold to has felt some version of that fear. These days I try to give them what I wanted back then: proof from someone in their position, and a first step small enough to undo.
Bought is the stage where the buyer has picked you and now has to act. Then they have to sign, pay or tell their boss, and many of them stop.
Most brands read that stop as a lost sale to a rival. Often there was no rival. The buyer simply did nothing. So they push harder at the moment the buyer is most afraid, which is exactly the wrong time to push.
The rival is doing nothing
In a considered purchase, your toughest competitor is the buyer's own inaction. Every proposal sits next to a free option: carry on as before.
Matt Dixon and Ted McKenna analysed about 2.5 million recorded sales calls from several dozen companies. Between 40% and 60% of qualified deals ended in no decision (Dixon). The buyer didn't pick anyone.
They then split those losses by cause. In 44% the buyer preferred the status quo. In 56% the buyer wanted to act but couldn't decide, out of fear of getting it wrong (Dixon and McKenna's deck).
One caveat. This comes from the authors' commercial book, The JOLT Effect. The sample mixes quick and complex sales, and nobody has replicated it. So I wouldn't claim that most lost sales everywhere are lost to nothing. Many are, and in complex business purchases it may be about half.
The reframing matters more than the exact figure. If the rival is doing nothing, you can't beat it with a better feature list. Doing nothing has no features. It wins by being safe.
Why doing nothing feels safe
Doing nothing wins because people tend to weigh a loss more heavily than an equal gain. A review of 607 estimates from 150 articles put the ratio at 1.955 (Brown, Imai, Vieider and Camerer). A loss hurts just under twice as much as the same gain pleases.
That idea isn't settled. David Gal and Derek Rucker reviewed the evidence and concluded it doesn't show that losses generally loom larger than gains (Gal and Rucker). I use the meta-analysis as the average, and their critique as a warning that the effect depends on the situation.
William Samuelson and Richard Zeckhauser named the second force in 1988. "Most real decisions," they wrote, "have a status quo alternative", and people choose it far more often than its merits suggest (Samuelson and Zeckhauser).
A third finding explains the fear. Ilana Ritov and Jonathan Baron found people would rather suffer harm from not acting than from acting. Their subjects refused a vaccine whose risk was smaller than the disease (Ritov and Baron). The scenarios were hypothetical, but the pattern is well known.
Put together, the three explain the stall. Buying and being wrong feels like your fault. Not buying and being wrong feels like bad luck. A nervous buyer will take bad luck every time.
One limit. For small amounts, one study found the pattern reversed: "gains loom larger than losses" (Harinck, Van Dijk, Van Beest and Mersmann). My reading is that fear matters most when the stakes are high. For a cheap, quick purchase, the problem at the last step is mostly friction.
Pressure loses sales. Safety wins them.
When a buyer stalls from fear, pressure makes the fear worse. Safety removes it.
Dixon and McKenna report that sellers win about 6% of deals with deeply indecisive buyers, while high performers win 31% (Dixon). Their deck adds that the usual pressure tactics backfire 84% of the time. That figure comes from the same dataset, and it's unreplicated.
The high performers judged the indecision, offered a recommendation, limited the exploration, and took risk off the table. None of those is a push.
I've seen it work from the seller's side. In 2021 the founder of a small consultancy reviewed our proposal for a new website with us, then went quiet for six weeks. When she finally wrote, it wasn't to say she'd chosen a rival. A long lockdown had stalled her main source of revenue, and she needed to keep cash in reserve. Doing nothing was the safe choice.
I didn't push. I told her I'd probably have made the same call in her shoes, and mentioned, with no pressure, that the cost could be spread over twelve months. Ten months later her team wrote back: a new financial year, a better position, were we still keen? She signed the original proposal unchanged, and she's still a client. Pressure would have won nothing that year, and might have cost us the next.
But scarcity usually works. The evidence doesn't say urgency always fails. Barton, Zlatevska and Oppewal combined 416 effect sizes from 131 studies. On average, scarcity raised purchase intention, and time-limited offers worked best for high-involvement products (Barton, Zlatevska and Oppewal). That's exactly where I argue against pressure. Two distinctions reconcile the finding with the method.
Real scarcity is information. If the price really rises on the first of the month, or only two install slots are left, say so. That helps them plan.
Manufactured pressure is a lie, and now it's unlawful. Arunesh Mathur and colleagues crawled about 11,000 shopping sites. They found 393 countdown timers, and 157 of them, on 140 sites, were deceptive: they reset, or the offer outlived the clock (Mathur and colleagues). In April 2026 an Australian court ordered Emma Sleep to pay AUD 15 million over false savings and countdown timers that reset (HWL Ebsworth).
So my working rule is this, and it's mine rather than a tested finding. A real deadline is fine, as long as a way out sits underneath it. Put the way out first and the deadline second.
Where the last step lives now
The last step increasingly happens on your own ground, after a machine has done the comparing.
Walmart let shoppers buy inside ChatGPT or click through to its own site. Purchases made inside the chat converted at a rate "three times lower" than those that went to the retailer's site (CNBC). CNBC also cites inaccurate item data and onboarding problems, so this isn't purely trust.
My reading: the machine suggests and the buyer pays where they trust. So the landing page has to repeat the machine's reason, and state the way out next to the price.
In business buying, the last step has also grown more crowded. G2 surveyed 1,038 software decision-makers in June 2026. 49% had seen a finance chief veto a purchase that was already approved. Finance involvement rose from 31% to 46%, and budget approval delayed 32% of purchases (G2).
How to tell it is failing
Proposals go quiet after a meeting that felt positive.
Your CRM's "lost" column says "no decision", "timing" or "budget" more often than a rival's name.
Buyers ask "can we get out of it?" or "what if it doesn't work?" near the end.
Checkout or sign-up analytics show people reaching the price, then leaving.
The finance or IT person first appears in the last week, with questions nobody prepared for.
The method: the risk removal ladder
The method has two parts. First, audit the last step for friction and fear. Then climb the ladder: remove the fears one rung at a time, starting with the lowest-risk step a buyer could take. The ladder is my working rule; each rung rests on evidence noted below.
The audit.
Name the rival. Write "doing nothing" at the top of your competitor list. For each lost deal last quarter, mark whether it went to a rival or to nobody.
Walk the last step yourself, as a first-time buyer, on a phone. Baymard Institute puts average cart abandonment at 70.22% across 50 studies (Baymard). Excluding "just browsing", 40% of US shoppers left over extra costs. 19% didn't trust the site with their card, and 18% were forced to create an account.
Map the fears, by person. Wasting money, looking foolish, being locked in, a failed rollout. Write each fear in the buyer's words.
The ladder. Five rungs, then an optional cap, in the order of the diagram.
A small first step. A trial, a pilot, a first month. Keep it short and active. One randomised trial covered 337,724 users at a large software firm. A 7-day free trial produced 5.59% more subscriptions than a 30-day one (Yoganarasimhan, Barzegary and Pani). Longer trials left people idle.
A way out. A money-back guarantee, lenient returns, or no lock-in. Experiments found guarantees raised purchase intention and willingness to pay a premium, more so for experience goods (Suwelack, Hogreve and Hoyer). A meta-analysis of 22 papers found refund leniency lifted purchases, though also returns (AMA summary of Janakiraman, Syrdal and Freling).
A plain recommendation. "If I were you, I'd pick this one, because…" A hard choice stalls, and a recommendation turns it into an easy one.
Proof from someone like them. One named customer in the same position, with a result.
Someone to call. A real person, with a name and a number, who answers. This rung is my addition.
The cap: an honest deadline, only if one exists. Test it first. Would it survive a regulator asking "what happens when the timer hits zero?" If not, remove it.
Sales, by hand
In considered and business purchases, a person still closes the sale. The salesperson's work is to confirm the reason, supply the proof and remove the risk, not to add urgency.
In owner-led sales, one person decides, and the risk is personal. They want a price, a timeline and someone to call. A short call with the owner often does more than a long proposal.
In committee sales, each person needs their own fear answered. Someone who walks out of the meeting frustrated, tired and confused defaults to doing nothing. Give your champion a one-page case they can forward without editing. G2's 49% suggests finance will read it, so write it for finance first.
When a deal goes quiet, the instinct is to chase. My working rule is the opposite. Make the next step smaller, and say so.
The bookkeeper's ladder
The bookkeeper for cafés is an invented example. Café owners are busy, and many have been burnt by an accountant before.
Rung
What she offers
The fear it removes
A small first step
One free Monday report, built from last month's takings and rosters
"It won't be worth the effort to hand over my numbers"
A way out
Monthly, no lock-in; cancel by email and keep your files
"I'll be stuck with someone useless"
A plain recommendation
"For one café, start with the weekly report. Add payroll when you trust me."
"I don't know which package I need"
Proof from someone like them
One café's twelve months of numbers, shown with the owner's permission
"That works for big places, not mine"
Someone to call
Her mobile number on the page; she answers before the morning rush ends
"I'll be talking to a call centre"
None of these cost her much. The free report takes an hour, and the monthly terms only cost her clients who would have left anyway.
Fieldline's last step
Fieldline, the invented scheduling-software firm, has reached the last step with Northgate Heating & Cooling. Dana now has a reason she can repeat. The CEO's question was "what does it cost us if it doesn't work?" Then nothing happened for five weeks.
The account manager's first draft was a "price rises next month" email. Instead, she mapped the fears.
Person
Their fear at the last step
The rung that removes it
Dana, head of operations (champion)
"If the technicians hate it, I'll wear it."
A small first step: a pilot in one depot, with the travel-time measure agreed before it starts
Ravi, finance lead
"This becomes a three-year cost we can't cancel."
A way out: an exit after the pilot with nothing owed beyond it, in writing
Mei, IT manager
"Security review will take months, and I'll get blamed for the delay."
Someone to call: Fieldline's security lead, plus the review questionnaire answered in advance
The CEO, who signs
"We change systems in our busy season and lose a quarter."
A plain recommendation: start after the peak, on one plan, named with the reason
All four
"Will this work for a firm like ours?"
Proof: a named contractor of similar size, and its pilot result
She sent Dana a one-page case written for Ravi and the CEO. It led with the cost of doing nothing: the hours lost to travel each week.
It didn't work. The CEO read the case, agreed the numbers were real, and said no. Northgate would stay with its spreadsheets for another year. The busy season was coming, two technicians had just left, and a new system felt like one more thing.
Fieldline did the one thing left. It sent a short email offering a smaller first step, ending "if now isn't the right time, just say so. I won't chase." Dana replied that it wasn't, and thanked them.
The story is invented, and I have made it end this way on purpose. Every rung was in place, and doing nothing still won. The ladder raises the odds of a yes; it doesn't make one certain. A method that claims to win every deal is selling you something.
What Fieldline kept was a champion who could repeat its reason, a CEO who had seen the numbers, and a door left open.
By mode
Each buying mode stalls at the last step for a different reason. Habitual and quick-choice buyers stall mostly on friction: a stock-out, hidden costs, a forced account, a long checkout. Fix the top two items from your walk-through first. Considered personal buyers fear a costly mistake that can't be undone, so lead with a way out. Owners carry the risk personally and have no one to ask: give them a plain recommendation and someone to call. Committees need each person's fear answered, a one-page case for finance and a scoped pilot. The friction and fear split is my reading of the small-stakes evidence, not a tested rule.
How Bought connects to the other stages
It needs a reason. The landing page must repeat the reason the buyer, or the machine, was given. Without it, the buyer arrives and finds a stranger.
It needs proof and answers. Proof from someone like them makes the risk feel small, and many last-step fears are questions that should already have been answered.
It feeds Kept. A way out only builds trust if you honour it, and keeping the customer starts the moment the first step ends.
What not to do
Don't fake the clock or the crowd. Resetting timers cost Emma Sleep AUD 15 million in Australia.
Don't make the first step long, or hide the total.
Don't treat a lost-to-nothing deal as dead. Leave the door open in writing, and keep the champion's reason alive.
How you know it worked
The Selectability Score (Part five) checks Bought on the page a buyer lands on. Does it repeat the reason they were given? Does it show proof? Does it give a clear next step? Where you have your own sales data, the score adds that too.
Then watch your own numbers.
The share of qualified deals ending in "no decision", tracked each quarter.
The time from proposal sent to yes or no.
The share of first steps (trials, pilots, free reports) that become paying customers.
Checkout or sign-up abandonment at the price step.
This afternoon
pull your last ten lost deals. Count how many went to a rival and how many went to nobody. Then walk your own last step as a buyer would, and note every surprise.
This quarter
build the ladder for your main moment. Add one small first step, state the way out next to the price, and name one recommended option.
Toolkit
The risk removal ladder. Use it once per moment, after the audit has mapped the buyer's fears at the last step. Start at the bottom rung and add each one before the next.
Read it from the bottom up. Each rung is a slightly bigger yes, and any deadline sits on top of the way out.
Every template for this stage is in the free Selectability Playbooks at rocmode.com/playbooks.
What we don't know
How big "no decision" really is. The 40–60% and the 44/56 split come from one proprietary dataset. No one has replicated it, and it mixes simple and complex sales.
Whether safety beats urgency head to head. I found no study comparing the two in high-stakes business buying. "Way out first, deadline second" is my working rule.
How much guarantees move real purchases. Most guarantee evidence is from lab studies of intention. I found no large field trial in business buying.
Whose evidence this is. Dixon and McKenna's data came from Tethr, a conversation-analytics firm where Dixon worked, and the authors sell JOLT training. G2 runs a software review marketplace. Baymard sells e-commerce research. Peer-reviewed sources: Brown and colleagues; Gal and Rucker; Samuelson and Zeckhauser; Ritov and Baron; Harinck and colleagues; Barton, Zlatevska and Oppewal; Suwelack, Hogreve and Hoyer; Janakiraman, Syrdal and Freling.